
A New Orleans tax attorney addresses founders who are the first in their families to build real wealth. The feature explains why keeping and passing on that wealth takes different skills than earning it, and gives a practical plan covering structure, advisers, family conversation and the transfer of knowledge.
By Dr. Tamara Patzer
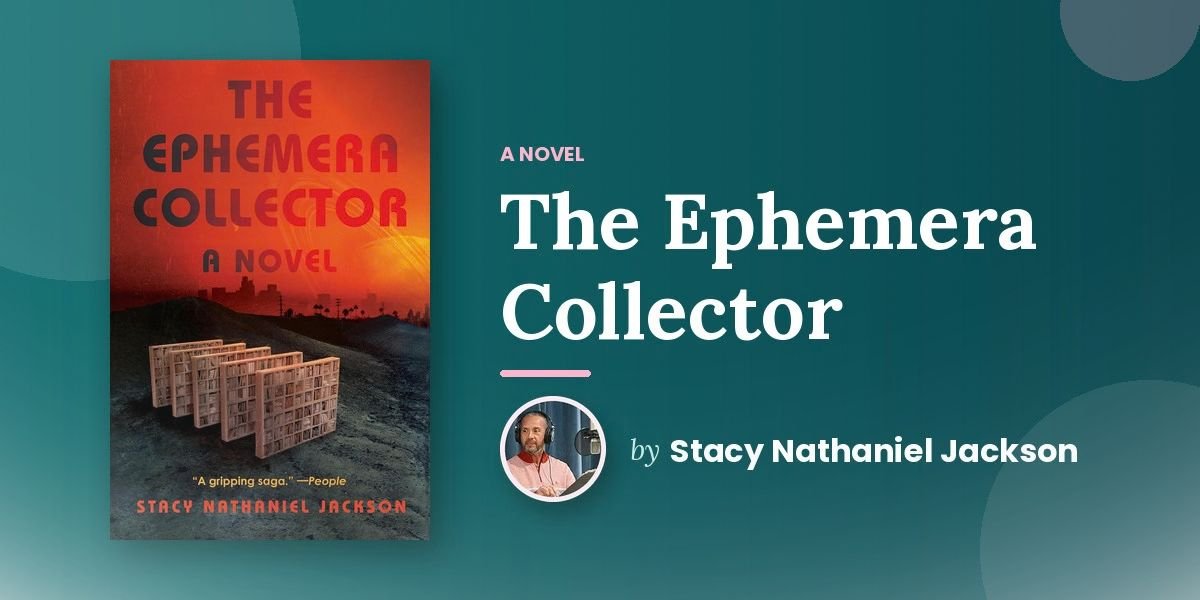
Building a company from nothing is one achievement. Making sure it still matters to your grandchildren is another. Founders who are the first in their families to build significant wealth often have no map for the second task, because no one before them did it. Todd M. Villarrubia, a New Orleans tax and estate attorney, speaks to that situation in Entrepreneurial B.E.A.S.T. Mode™. He begins with a plain statement of what separates families that keep wealth: “Families who successfully sustain wealth across generations share more than just good fortune; they share structure, intention, and open communication.”
What changes between earning wealth and keeping it?
The skills. Earning rewards speed, risk and personal drive. Keeping rewards structure, patience and teamwork. The book makes the point through a founder who understood the difference: “But Francisco understood something most founders don’t: building value and preserving value require different skill sets.”
That does not mean a founder must change character. It means the founder should add people and habits that cover what they do not do naturally. The founder who is generous, bold and quick may need an adviser who is careful, slow and methodical. Both are needed. The founder’s instinct to move fast is the reason the company exists, and the adviser’s instinct to slow down is the reason it may continue to exist. A good team lets each instinct do its job at the right moment.
How much does enough really take?
It depends on whom you ask. Charles Schwab’s 2025 Modern Wealth Survey found that Americans think it takes about $2.3 million to be considered wealthy and $839,000 to be financially comfortable1. Those numbers are opinions, not rules, but they show how personal the target is.
The Federal Reserve’s 2025 Survey of Consumer Finances, released October 9, 2026, put median family net worth at $215,900 and mean net worth at $1.24 million2. A family that crosses either line has started building something. The question is whether it will last past the person who built it.
Why does the second generation matter so much?
Because that is where most plans are tested. The founder’s presence holds the structure together. When the founder steps back, the structure has to hold on its own. The book describes the aim: “treat wealth like a business, not a windfall, and view legacy as a mission, not an accident.”
Cerulli Associates expects $124 trillion to move between generations in the United States through 2048, with $105 trillion going to heirs and $18 trillion to charity3. Every one of those dollars has a first generation behind it. The families who benefit most will be those that prepared the next generation as well as the next transfer.
What should a first-generation founder put in place?
Five things, in rough order.
First, a structure that separates risks. The book’s principle is plain: “The principle is simple: separate entities for separate risks.” A founder who owns everything personally has put the family home, the savings and the company in the same basket.
Second, a team that works together. A good attorney, accountant and financial adviser should know each other and meet at least once a year.
Third, documents that match the facts. Wills, trusts, beneficiary forms and business agreements should all say the same thing about who gets what and who decides.
Fourth, a written statement of purpose. Why does the family hold this wealth, and what should it do?
Fifth, a plan for the next generation to take part. Children can attend meetings, learn the vocabulary and take on small responsibilities well before they hold any control.
How should a founder talk with children about money?
Early, in plain words, and more than once. The conversation should cover where the wealth came from, what the founder hopes it will do and what the children can expect. It should also cover what they cannot expect. The book warns of a familiar failure: “Entitlement supplants stewardship; children expect wealth without understanding responsibility.”
A family that explains the work behind the money gives its children a better chance. A family that stays silent leaves them to guess.
What is the role of shared purpose?
It is the glue. The author puts it strongly: “Without a shared purpose and values, even the best estate plan becomes fuel for division.” Documents say who owns what. Purpose says why it matters. When the two are present together, disputes tend to be smaller and easier to settle.
Purpose does not have to be grand, and it can change as the family grows. It can be as simple as keeping the company independent and helping the next person start one. What matters is that the family has said it out loud and agreed.
What is a realistic first step?
Pick one hour this month. Write down who your advisers are, what documents exist and who knows where they are. Then write three sentences about why you built what you built. Share the page with one trusted adviser and ask what is missing. That one hour will teach you more about your readiness than a dozen articles. Many founders discover they know exactly what they want but have never written it where anyone else could find it. Putting it on paper is the first step in turning a private intention into a family plan, and it costs nothing but attention.
Bring the same page to the next conversation with your children, at whatever level suits their ages. Ask them what they think the family’s wealth is for. The answers are often surprising, and they tell you where to begin.
If a gap shows up, seek legal advice on how to close it. The earlier a gap is found, the cheaper it is to fix.
Common questions
Is this only for very wealthy founders? No. The book argues that wealth level is not the only test, and many modest estates benefit from structure and communication.
Should heirs be involved before the founder retires? Often yes, in age-appropriate ways. Ask your advisers how to phase it.
What if there is no family successor? Then the plan should say who will run the company, who will own it and how value will be shared. Seek legal advice about options.
Sources
- Charles Schwab, 2025 Modern Wealth Survey (Business Wire)
- Federal Reserve Board, press release on the 2025 Survey of Consumer Finances
- NAPA-Net, Wealth Transfers Expected to Hit $124 Trillion Through 2048 (reporting Cerulli)
About the author. Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.
About the source. Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™. Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124. Phone: 504-982-8207; email: todd@lawealthplan.com; website: https://lawealthplan.com/?utm_source=newsanchored&utm_medium=blk-news&utm_campaign=family-office
Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.