BLK News

How to Prepare for a Working Capital Loan Application
Working capital is the money that keeps ordinary operations moving: payroll, rent, inventory, insurance premiums, and the bills that arrive before your customers pay. When that cushion thins out, borrowing can feel like the only way through. The better approach is to look at how other businesses face the same squeeze, because the right move depends heavily on what caused it.

Below are three common situations, followed by the steps that apply to all of them. For a wider view of the market, this list of hybrid funding options for business owners shows how different models work.

The Restaurant Facing a Seasonal Dip

Maria runs a 60-seat restaurant in a beach town. Sales drop by 40% after Labor Day, but her rent, insurance, and core staff costs don’t. She wants $25,000 to carry the business through October.

What makes her file strong: steady card deposits and three clean months of statements. Underwriters can see the seasonal pattern clearly, especially if she supplies last year’s statements for the same months.

What she needs to watch: the repayment schedule. Payments set against her slowest weeks could create the very shortage she is trying to prevent. For her, a schedule that accounts for the seasonal dip may be worth a slightly higher cost.

The lesson: match the payment rhythm to your revenue rhythm, not just the amount to your bill.

The Contractor Waiting on a Big Payment

Devon’s electrical company finished a $180,000 commercial job. The general contractor pays in 60 days, yet Devon must cover materials and crew wages on the next project starting Monday. He wants $50,000.

What makes his file strong: a signed contract, consistent deposits, and an invoice with a known due date. Lumpy revenue is normal in construction, so a short explanation of the deposit pattern can prevent underwriter questions.

What he needs to watch: term length. He knows when the cash will arrive, so an agreement that lets him pay off early and actually save money is valuable. Not every agreement reduces the total cost when you repay ahead of schedule.

The lesson: if you know exactly when the money returns, ask what prepayment is really worth before signing.

The Online Retailer Buying Ahead

Priya sells home goods online. A supplier offers a 12% discount for a bulk order placed this week ahead of the holiday season. She wants $35,000.

What makes her file strong: platform sales reports paired with bank statements that show payouts landing as expected.

What she needs to watch: the math. A 12% supplier discount sounds attractive, but if the financing costs 18% over four months, the purchase only makes sense when the extra inventory actually sells at full margin. Borrowing to save money works only when the savings exceed the cost.

The lesson: calculate the return on the specific purchase, not the appeal of the deal. Options such as Fundivi working capital funding are one place to begin pricing that kind of purchase, alongside your bank and other online providers.

Common thread: All three owners have an identifiable reason, a visible revenue stream, and a plan for repayment. Those three things are what a lender’s decision rests on.

The Sequence That Applies to All Three

Step 1: Pin down the number

Build a simple 13-week cash forecast, even on a single sheet. List expected receipts and payments by week. The lowest balance in that forecast tells you how much you actually need. Owners who skip this step tend to borrow a round number that’s too high, or one that’s too small and leads to a second, more expensive request.

Step 2: Prepare the documents before you apply

Most working capital providers focus on recent cash flow rather than long financial packages. Expect to provide:

• Three to six months of full business bank statements

• Photo identification for the main owners

• Business formation details and your EIN

• Processor or platform statements, if card or online sales are significant

• A list of current business debts, including payment amounts

Step 3: Apply early and compare at least two offers

File in the morning on a weekday. Use prequalification where you can, and ask whether each inquiry is soft or hard.

Step 4: Compare offers on the same terms

Question

Offer A

Offer B

Net cash received after fees

Write it here

Write it here

Total amount repaid

Write it here

Write it here

Payment amount and frequency

Write it here

Write it here

Approximate APR

Write it here

Write it here

Savings for early payoff

Yes or no

Yes or no

Personal warranty or lien

Yes or no

Yes or no

Fill in this table yourself using only the figures in the written offer. Representatives often quote a “payment as low as” figure, and that number on its own does not tell you the full cost.

Step 5: Confirm who you are borrowing from

Before you sign, find out who will actually fund the agreement and who you will contact once it is in place. Some providers handle underwriting, funding, and servicing themselves, while others involve outside institutions at one or more of those stages. Providers that publish how their process is organized, as Fundivi does in its business lending platform announcement, make that easier to check. Ask directly whose name will appear on the contract.

Step 6: Sign, confirm the transfer method, and watch the first debit

Ask whether funds travel by wire or ACH and what the daily cutoff is. Then check your account on the first scheduled payment day. Errors are easier to resolve in the first week than the fifth.

When a Working Capital Loan Is the Wrong Answer

Borrowed money solves timing problems. It doesn’t solve profitability problems. If your business loses money every month, new debt adds a payment on top of the loss and shortens your runway. Before borrowing, look at whether you could do any of the following:

• Ask key vendors for 15 to 30 more days

• Offer a small discount for early customer payments

• Sell slow-moving inventory at a modest markdown

• Draw on an existing credit line at a lower cost

• Speak with a local Small Business Development Center about free counseling

Be careful, too, about taking on a new obligation while an older one is still running. Two payments drawn from the same thin margin is a common route into serious cash trouble, and many agreements restrict it outright.

Reading Your Own Bank Statements First

Spend fifteen minutes reviewing your statements the way a reviewer will. Add up true revenue deposits for each month and leave out owner transfers, loan proceeds, and refunds, because underwriters remove them too. Count the days your balance went negative, and note the average balance you carried. Then mark any recurring debit that belongs to another lender. If those figures look weaker than you expected, it’s better to learn that now and request a smaller amount than to find out through a decline. A short note explaining an unusual month, such as a burst pipe or a one-time tax payment, gives the reviewer context that the numbers alone can’t supply.

Frequently Asked Questions

How much working capital can I expect to qualify for?

It depends on your deposits. Many providers size offers around a portion of monthly revenue, and larger requests usually need more documents and more time.

Do I need collateral?

Often not specific collateral, but many unsecured working capital products still involve a personal warranty and a general lien on business assets. Read this section of the contract closely.

Can I use the money for payroll?

Generally yes. Payroll, rent, inventory, and similar operating costs are typical uses. Check the agreement for any restrictions on use of proceeds.

What if my revenue is seasonal?

Provide statements covering a full year if possible, and look for a repayment schedule that accounts for your slow months. Showing last year’s rebound helps underwriters read a weak month correctly.

Can I refinance a working capital loan later?

Often, once you have a payment history. Before doing so, check whether the agreement reduces the total cost when you repay early, since some do not.

How can I tell whether an offer is too expensive?

Convert it to total dollars and approximate APR, then compare it with the profit the money will generate. If the cost exceeds the expected gain, the offer is too expensive for that purpose.

Disclaimer: This content is for informational purposes only and is not intended as financial advice, nor does it replace professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.
Black on the Block Brings Its Touring Black-Owned Marketplace to Charlotte on November 8, Five Years After Its Los Angeles Start

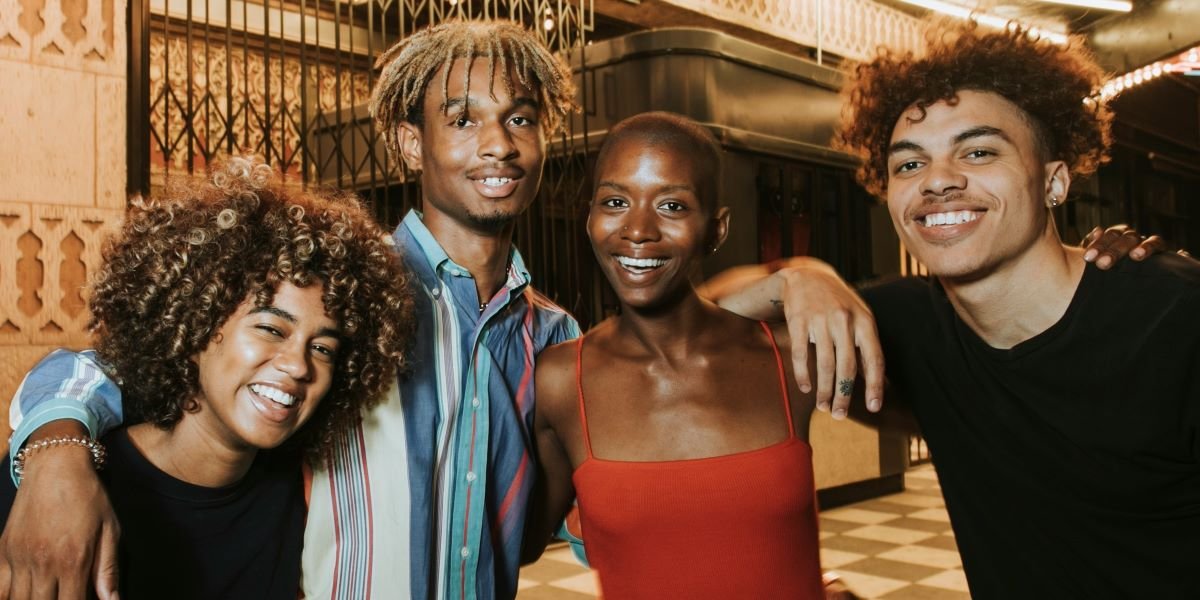
Black on the Block, the touring marketplace for Black-owned businesses, sets up in Charlotte on Sunday, November 8, 2026. Founded in Los Angeles in June 2021 by sisters Lanie and Char Edwards, the event has grown from a local pop-up into a monthly series that travels to cities across the country.

Key Takeaways

  • Black on the Block holds its Charlotte marketplace on Sunday, November 8, 2026.
  • Sisters Lanie and Char Edwards founded Black on the Block in Los Angeles in June 2021.
  • A 2025 partnership with Live Nation Urban expanded the event to seven cities, including Charlotte, Atlanta, Houston, Detroit, and Washington, D.C.
  • The founders say the marketplace generated more than $4 million in consumer spending with Black-owned businesses in 2025.
  • Black on the Block Community Outreach, the brand’s nonprofit, offers vendor fee grants, training programs, and funding for Black entrepreneurs.

Black on the Block Sets Up in Charlotte This Sunday

Black on the Block arrives in Charlotte on Sunday, November 8, bringing its mix of Black-owned vendors, food, music, and community gathering to the Queen City. The event is built around one idea: give Black-owned businesses a shared, high-traffic space where customers come specifically to find them.

Local business leaders are backing the stop. The Charlotte Mecklenburg Black Chamber of Commerce has described the event as a chance for Black-owned businesses to generate revenue, grow their customer base, and build visibility, and it has encouraged the community to turn out. Visitors planning to attend should check Black on the Block’s official channels for the venue, hours, and entry details.

Black on the Block Started as a Los Angeles Pop-Up in 2021

Black on the Block began in Los Angeles in June 2021, as small businesses were recovering from the disruption of the pandemic and in-person shopping was returning. Lanie and Char Edwards understood the vendor side of that market firsthand. Both ran their own clothing brands, Lanie with Cosier and Char with Upstreet Kid, so they knew how hard it can be for a small brand to get in front of customers.

The sisters built an event where Black-owned businesses were the entire lineup rather than a few booths in a larger market. The format took off in Los Angeles and soon began drawing interest from other cities, turning a local pop-up into a recurring series.

A 2025 Partnership Turned the Marketplace Into a National Tour

Black on the Block’s expansion moved faster in 2025, when Live Nation Urban partnered with the founders to take the vendor festival to seven cities: Arlington, Atlanta, Houston, Los Angeles for a Juneteenth festival, Detroit, Washington, D.C., and Charlotte. The Edwards sisters described the partnership as a shared win for vendors, attendees, and the Black on the Block community, giving them the resources to reach new markets.

The marketplace now runs as a monthly traveling event that draws thousands of attendees, and its stops have included Dallas, Houston, Washington, D.C., Chicago, Charlotte, and Atlanta. In June 2026, Black on the Block returned home to mark its fifth anniversary with a Juneteenth festival at Los Angeles Center Studios, bringing together more than 150 vendors, performers, and community members.

Why a Traveling Marketplace Matters for Black-Owned Businesses

Black on the Block’s model addresses a practical problem for small businesses: getting in front of enough customers at once. A single well-attended market day can introduce a brand to more shoppers than weeks of online posts. For many vendors, a booth is also a low-commitment way to test products, meet customers face to face, and build a following before investing in a storefront.

The founders say the marketplace generated more than $4 million in consumer spending with Black-owned businesses in 2025. That spending reaches a business community that has grown steadily in recent years, with more than 200,000 Black-owned businesses with paid employees now operating across the United States. Events like Black on the Block help connect many of the smaller brands in that pipeline with customers who are looking for them.

The touring format also spreads that access across regions. Instead of asking vendors to travel to one large annual festival, Black on the Block brings the marketplace to them, so a Charlotte vendor can sell to a home crowd while being part of a national brand.

Black on the Block Community Outreach Supports Vendors Beyond Event Day

Black on the Block’s work continues after the booths come down. The brand set up Black on the Block Community Outreach, a 501(c)(3) nonprofit, to provide vendor fee grants, training programs, resources, and funding for Black entrepreneurs. The vendor fee grants address a common barrier: the cost of a booth can keep newer businesses out of the markets that could help them grow.

Five years after its first Los Angeles pop-up, Black on the Block has become a moving marketplace and a support network at the same time, and Sunday’s Charlotte stop puts that model in front of another city’s entrepreneurs and shoppers.


FAQs

When Is Black on the Block in Charlotte?

Black on the Block holds its Charlotte marketplace on Sunday, November 8, 2026. Venue, hours, and entry details are available through Black on the Block’s official website and social channels.

Who Founded Black on the Block?

Sisters Lanie and Char Edwards founded Black on the Block in Los Angeles in June 2021. Both also run their own clothing brands, Cosier and Upstreet Kid.

What Is Black on the Block?

Black on the Block is a touring marketplace that showcases Black-owned businesses alongside food, music, and community programming. It runs monthly events in cities across the United States.

Which Cities Has Black on the Block Visited?

Black on the Block has held events in Los Angeles, Dallas, Houston, Atlanta, Chicago, Washington, D.C., and Charlotte. Its 2025 expansion schedule also included Arlington and Detroit.

Madam C.J. Walker: How Sarah Breedlove Built a Hair Care Empire on a Network of Black Women Agents

Madam C.J. Walker, born Sarah Breedlove in Delta, Louisiana, in 1867, built a hair care and beauty company for Black women in the early 1900s. From an Indianapolis base, she sold her products largely through personal sales agents, training several thousand Black women who found financial independence through her business.

Key Takeaways

  • Sarah Breedlove was born on December 23, 1867, in Delta, Louisiana, the first child in her family born into freedom after the Emancipation Proclamation.
  • She took the name Madam C.J. Walker after marrying Charles Joseph Walker in 1906.
  • In 1910 she moved her business to Indianapolis, setting up a laboratory and beauty school, and she incorporated her company in 1911.
  • By the time of her death, the company employed several thousand agents and had brought in more than half a million dollars in sales.
  • She died on May 25, 1919, at Villa Lewaro, her estate in Irvington-on-Hudson, New York.
  • Her daughter, A’Lelia Walker, became president of the company and a patron of the Harlem Renaissance.

Who Was Madam C.J. Walker Before the Business

Madam C.J. Walker’s early life offered few signs of what she would build. Born Sarah Breedlove on December 23, 1867, to Owen and Minerva Anderson Breedlove, she was the first child in her family born into freedom after the Emancipation Proclamation. She lost both parents by age seven, married at fourteen, gave birth to her only child at seventeen and was widowed at twenty.

As a young widow, she supported her daughter, Lelia, through hard physical labor. Those years shaped both her drive and the message she later carried to other Black women: that skilled, independent work could replace the low-paid labor that defined so many of their lives.

How Madam C.J. Walker Built Her Hair Care Business

In 1906, Sarah Breedlove married Charles Joseph Walker and began marketing herself and her products under the name Madam C.J. Walker. Her signature product, Madam C.J. Walker’s Wonderful Hair Grower, found early success, and she moved her operations as the business grew, first to Pittsburgh in 1908, where she opened the Lelia College of Beauty Culture, named for her daughter.

In 1910, Walker settled in Indianapolis, where she set up a laboratory and a beauty school and established the Madam C.J. Walker Manufacturing Company. She incorporated the company in September 1911, with Indianapolis remaining its hub even after she moved to New York.

The Walker Agents Were the Engine of the Company

Walker’s business model is what set it apart. Sales were made largely through personal agents rather than stores, with only a few wholesale distributors in large cities. Each agent was trained in the Walker method, which turned the sales force into a network of skilled beauty professionals.

In 1916, Walker began organizing her agents into state and local chapters, and in 1917 she hosted the first national convention of Walker “beauty culturists.” The convention honored agents who sold the most products and chapters that raised money for charitable and social causes, rewarding community giving alongside sales.

For Walker, the purpose was economic independence. Her business gave women a way, in her words, to “abandon the wash-tub for more pleasant and profitable occupation.”

Madam C.J. Walker’s Wealth, Philanthropy and Later Years

Walker’s annual sales grew between 1911 and her death, and by the end of her life the company had brought in more than half a million dollars in sales through several thousand agents. Records held by the Indiana Historical Society note that she was repeatedly described as a millionaire in her final years.

As her wealth grew, Walker gave increasing amounts to African American causes. Around 1916, she began living in New York, first at a Harlem townhouse, and in 1918 she moved into Villa Lewaro, a mansion in Irvington-on-Hudson designed by the Black architect Vertner Tandy. She died there on May 25, 1919, at age 51.

Madam C.J. Walker’s Daughter Carried the Legacy Forward

After Walker’s death, her daughter, A’Lelia Walker, became president of the company. She also became a patron of the Harlem Renaissance, hosting a cultural salon known as the Dark Tower at her Harlem townhouse during the 1920s. A’Lelia Walker died in 1931.

The family’s legacy remains visible in its buildings. The Madam Walker Legacy Center, built in 1927 as the Walker Theatre on property Walker purchased in downtown Indianapolis, stands as a tribute to her. Villa Lewaro is a national historic landmark and has been named a national treasure by the National Trust for Historic Preservation.

FAQs

Who is Madam C.J. Walker?

Madam C.J. Walker, born Sarah Breedlove in 1867, was a businesswoman who built a hair care and beauty company for Black women. Her company, based in Indianapolis, sold its products through several thousand trained sales agents.

Who was Madam C.J. Walker’s daughter?

Her daughter was A’Lelia Walker, born in 1885. After her mother’s death in 1919, she became president of the company and a patron of the Harlem Renaissance, and she died in 1931.

When did Madam C.J. Walker die?

Madam C.J. Walker died on May 25, 1919, at age 51. She died at Villa Lewaro, her estate in Irvington-on-Hudson, New York.

What is the Madam Walker Legacy Center?

The Madam Walker Legacy Center is a building in downtown Indianapolis, built in 1927 as the Walker Theatre. It stands on property Walker purchased and serves as a tribute to her legacy.

What did Madam C.J. Walker say about her business?

Walker described her business as a way for women to “abandon the wash-tub for more pleasant and profitable occupation.” She also said of her Indianapolis operation, “I have built my own factory on my own ground.”

How Global Author Publishing’s Children’s Book Writing Services Help Authors Tell the Stories Kids Need

A child who opens a book and finds a hero with their hair, their skin tone and their family traditions learns something that lasts: stories like theirs belong in books. Parents, teachers, pastors and community leaders across the country want to write those stories, and many are doing it with professional children’s book writing services. The goal is simple and powerful: more books where children see themselves at the center of the adventure.

Why Representation on the Page Matters

Literacy scholar Rudine Sims Bishop famously described children’s books as mirrors, windows and sliding glass doors. A mirror lets a child see their own life reflected with dignity. A window lets other children see into lives different from their own. The best picture books do both at once.

Authors who grew up without those mirrors often feel the gap most clearly. Many remember searching library shelves for characters who looked like them and coming up short. Writing a children’s book is one way to make sure the next generation has more to choose from.

What Children’s Book Writing Services Bring to the Story

Writing for children looks easy until you try it. A picture book may have only a few hundred words, and every one has to earn its place. Professional children’s book writing services help authors with:

  • Language that fits the reader’s age, from toddlers to early chapter books
  • Read-aloud rhythm that makes a story fun to share at bedtime or in the classroom
  • Page-turn pacing that builds anticipation
  • A message that lands without sounding like a lecture

The author’s voice and cultural knowledge stay at the heart of the book. A good writing partner listens first, then helps shape family memories, community history or a child’s everyday joy into a story young readers will ask for again. Authors who also want a companion guide for parents or educators can turn to professional eBook writing services for authors.

Bringing Characters to Life With Care

In a children’s book, the art carries as much meaning as the words. Children book illustration services should portray skin tones, hairstyles, clothing and homes with accuracy and warmth, because children notice every detail. Authors should expect to review character sketches and give feedback before final artwork begins.

Professional book cover design services then turn that art into a cover that stands out on a crowded shelf. Book formatting services arrange text and pictures across each spread so the story flows naturally from page to page.

Polishing and Publishing the Book

Before printing, professional book editing services check every line while respecting the author’s voice, including dialogue that sounds the way real families talk. Authors can then order copies for schools, churches, libraries and book fairs through online book printing services.

Ownership matters here. When choosing the best book publishing company, authors should ask directly who owns the rights and the final files. Comparing the best book publishers on that question protects both the story and the author’s legacy.

Reaching Families, Classrooms and Communities

A finished book needs a path to its readers. Book marketing services connect authors with parents, educators and local organizations. Book trailer services create short videos that bring characters to life on social media. Author website design services give families a place to find the book, and SEO content writing services help that site appear when parents search for diverse children’s books.

Audio opens another door. The best audiobook services can turn a picture book into a warm read-aloud recording for car rides, bedtime and young listeners who are still learning to read.

Your Story Can Be Someone’s Mirror

Every child deserves to open a book and recognize their own world. Children’s book writing services help authors turn that belief into a finished, beautifully illustrated book. Global Author Publishing, which offers children’s book publishing and illustration design, invites writers to start with a free author consultation.

Burt Pinnock and the Growing Role of Memorial Architecture in Preserving African American History Through Public Spaces

In recent times, memorial architecture within the United States has increasingly become an approach used to examine and analyze certain difficult aspects of the country’s past. In recent years, universities, towns, and cultural organizations have provided funding for projects that acknowledge the legacy of slavery and racism, and create places of memory through memorial architecture. Most of these projects have involved integrating architecture, archaeology, historiography, and the community instead of relying only on traditional approaches to memorial. This has emerged in recent years as organizations reevaluate the role played by history in public space. From this approach, the architect is more than a designer.

Burt Pinnock has become associated with several of these efforts through projects that combine architecture with cultural heritage and public history. Based in Richmond, Virginia, Pinnock has worked on memorials and preservation initiatives that examine African American history through the built environment. His work has frequently involved partnerships with local governments, universities, historians, archaeologists, descendant communities, and nonprofit organizations. Rather than treating memorials as isolated structures, many of these projects have developed through extended public consultation and historical research before architectural concepts were finalized. This collaborative approach has become a recurring feature of his professional practice.

One of the largest projects associated with Pinnock is the Shockoe Project in Richmond. Led by the City of Richmond, the initiative seeks to preserve and interpret one of the nation’s most significant sites connected to the domestic slave trade. The city states that the project includes improvements to the Richmond Slave Trail, the Shockoe Bottom African Burial Ground, Lumpkin’s Jail, Reconciliation Plaza, the planned Shockoe Institute, and recommendations for a National Slavery Museum experience. The city has allocated approximately $58 million for the initiative through municipal, state, and philanthropic funding, including support from the Mellon Foundation. Baskervill, led by Pinnock, serves as the design team for the overall project.

The Richmond Slave Trail represents another long-running preservation effort connected with Pinnock’s work. The trail links locations that illustrate Richmond’s role in the domestic slave trade while providing historical interpretation throughout the city. The next stages of the Shockoe Project have brought together the development of the memorial trail as a part of a greater strategy that involves connecting memorial landscapes, archaeology, educational opportunities, and gathering spaces. This approach to memorializing is described in the city’s master plans as creating an interconnected destination that fosters understanding of history in many places instead of focusing on a particular monument.

Pinnock has also worked on memorializing institutional history at universities. At William & Mary, he was the architect of record for the Hearth: Memorial to the Enslaved, which acknowledges almost 170 years of the presence of enslaved labor within the university. The memorial resulted from years of research and consultation with students, faculty members, descendants, and community members. This project is professionally acknowledged by receiving the National Organization of Minority Architects Honor Award. The university represents the memorial as part of a broader initiative to address its institutional history and relationships with slavery through a memorial public space.

At the University of Richmond, Pinnock’s work includes designing a Burying Ground Memorial after years of research and public consultation. The university-sponsored research revealed the location of a burial ground of the enslaved and previous disturbances that took place there during campus development. The memorialization committee was created in 2020 with the help of descendant representatives, historians, archaeologists, faculty members, and community representatives to make recommendations. With the help of ground-penetrating radar surveys and archaeological investigations, the plan to preserve the historic topography of the space and leave the sacred land undisturbed was developed. Construction started in 2024, and the memorial opened in 2025.

Another project associated with Pinnock’s portfolio is the Virginia Civil Rights Memorial Plaza in Richmond. According to AIA Virginia, his work has included planning and design contributions connected with the plaza alongside projects for the Black History Museum and Cultural Center of Virginia and the Richmond Slave Trail Commission. These commissions reflect a consistent focus on civic spaces that combine historical interpretation with contemporary public use. Rather than approaching preservation as the restoration of buildings alone, the projects frequently integrate landscape architecture, interpretive features, and community participation to strengthen public understanding of historical places.

The methods used across these projects share several common characteristics. Historical research is conducted alongside architectural planning. Archaeological investigations inform design decisions where appropriate. Descendant communities participate in workshops and consultations before concepts are finalized. Public institutions contribute historical records and educational resources. These processes demonstrate how memorial architecture has increasingly become a collaborative field involving multiple disciplines rather than architecture alone. Pinnock has discussed similar ideas in public lectures and his published essay A Modern Imperative, where he argues that architecture should respond to broader civic responsibilities instead of functioning solely as a design exercise.

Overall, these projects have helped contribute to larger conversations about how difficult histories have been remembered in the American built environment. There have been more instances of cities and universities recognizing the need for memorials, historic landscapes, and public sites to remember histories which have not received much public recognition in the past. As part of this larger trend, Burt Pinnock has worked on projects that have combined architecture, preservation, archaeology, and community involvement to help create places for memory, learning, and discussion. In contrast to the traditional use of a single monument, he has mostly focused on landscapes and public spaces that may help history remain part of civic discourse.

Multi-Location Businesses: Planning Expansion Financing Before You Need It

Opening a second, third, or fourth location raises financing questions that differ from those a single-location business typically faces. A business owner planning expansion benefits considerably from checking their standing well before the actual need becomes urgent, rather than scrambling once a lease is already signed.

Why Expansion Financing Deserves Advance Planning

A single-location business facing a routine cash flow gap can often address that need reactively, applying once the gap becomes apparent. Expansion is genuinely different: a new location typically involves a known timeline, a build-out or lease deposit with a specific due date, and a considerably larger capital requirement than routine working capital needs. This predictability creates a genuine opportunity to plan financing well in advance, rather than discovering qualification issues at the exact moment they’re most costly to address.

Checking Qualification Before the Lease Is Signed

Fundivi, a direct lender and hybrid funding platform, built its self-underwriting engine specifically to let a business owner check this kind of standing well before any commitment is made. A business owner considering a second location benefits enormously from running their current numbers through the tool before signing a lease, so they can clearly see whether their existing revenue, balance, and leverage position realistically supports the additional financing the expansion will likely require.

Why Leverage Matters Especially Heavily for Multi-Location Growth

A business already carrying financing tied to its original location needs to weigh that existing obligation carefully against any new expansion-related request. Fundivi’s engine treats leverage above 25% of revenue as a real constraint on how much new financing a business can access, so business owners should calculate their current leverage honestly before assuming expansion financing will be readily available on top of an existing obligation.

This matters because expansion revenue doesn’t materialize immediately. A new location typically takes time to reach the same revenue level as an established one, so the underwriting calculation at the time of opening reflects only the original location’s revenue, not the combined revenue a business might reasonably expect once expansion is complete.

Choosing the Right Product for Expansion

The funding product matcher becomes particularly useful for expansion planning, since a defined, one-time expansion cost, build-out, equipment, or a lease deposit, often points toward a term loan’s fixed structure rather than a more open-ended product built for ongoing operational needs. A business owner clear on the specific, one-time nature of expansion costs can use this clarity to guide a more informed product selection from the start.

Why Timing the Application Matters

Because expansion typically involves a known future date, a business owner benefits from timing their application to allow genuine buffer before that date arrives, rather than applying at the last possible moment. This buffer allows time to address any qualification gap the underwriting engine might reveal, whether that means paying down existing leverage or building a stronger cash position, before the actual expansion deadline arrives.

Why Multi-Location Businesses Face a Genuinely Different Risk Calculus

A single-location business considering financing weighs the request against one operating unit’s revenue and cash flow patterns. A multi-location business weighs the same decision against a considerably more complex picture, since the existing locations’ combined performance, not any single location in isolation, determines the overall qualification standing that any new expansion financing gets evaluated against. A business owner managing multiple locations should think of their qualification profile as a genuinely combined picture, one where a strong original location can support expansion financing even if a newer, still-developing location isn’t yet contributing meaningfully to revenue.

This combined view also means a business owner should pay attention to how each location’s performance affects the overall leverage and revenue calculations that feed into any qualification check. A struggling second location, even while a first location remains strong, can meaningfully drag down the combined numbers a lender or the underwriting engine actually evaluates, something a business owner should account for honestly rather than assuming their strongest location alone determines the outcome.

Sequencing Multiple Expansion Financing Needs

A business planning several locations over multiple years benefits from thinking through the sequencing of financing needs across that entire timeline, rather than treating each expansion as an entirely isolated decision. Because leverage accumulates across obligations, a business that takes on meaningful debt for a second location should factor in how that obligation affects its capacity to finance a third location on a similar timeline, potentially planning a longer gap between expansions or prioritizing faster repayment on earlier obligations to preserve genuine capacity for future growth.

Why a Struggling New Location Shouldn’t Derail Plans for Future Growth Entirely

A newer location underperforming expectations during its early months is a genuinely common pattern, not necessarily a signal that further expansion is unwise. Most new locations take meaningful time to reach the revenue level of an established one, and a business owner planning a third or fourth location should factor this typical ramp-up period into their overall timeline rather than assuming an early, softer performance at location two permanently rules out further growth. Checking the combined qualification picture periodically as a newer location matures gives a genuinely more accurate read than a single early snapshot ever could.

How the Hybrid Model Specifically Supports Multi-Location Growth

Fundivi’s broader hybrid structure, combining direct lending with a network of vetted partners, offers a particular advantage for multi-location businesses managing several rounds of financing over time. Rather than needing to separately search for a new lender each time a new location’s financing needs arise, a business owner can return to the same coordinated relationship, one that already has context on the business’s history and can evaluate each new request, whether directly or through a partner, against that established understanding.

Frequently Asked Questions

How far in advance should I check my qualification for expansion?

Checking several months before any lease commitment gives genuine time to address any gap the tool reveals, rather than discovering an issue only once the timeline has already become urgent.

Does existing financing on my first location automatically disqualify me for expansion financing?

Not automatically, though it does factor into your leverage calculation, which may size down how much new financing is realistically available depending on your current obligation load.

Should I wait until the new location is generating revenue to apply?

This depends on your specific timeline. Many expansion costs, like a lease deposit or initial build-out, must be covered before the new location can generate any revenue.

Does the underwriting engine account for projected revenue from a new location?

No. The tool evaluates your current numbers as they stand today, not projected future revenue from a location that hasn’t yet opened.

What if my expansion timeline changes after I’ve already checked my numbers?

Rechecking periodically as your timeline evolves keeps your understanding of your standing aligned with your actual plans.

Getting Started

Business owners planning expansion can check their current standing well before any commitment, confirm which product fits their specific expansion cost, and, once an offer arrives, use the cost calculator to confirm it’s genuinely sustainable alongside existing obligations. For more detail on financing multi-location growth, Fundivi’s resource library covers the specifics in plain language.

Disclaimer: This content is for general informational purposes only and should not be considered as financial advice. The content is not intended to be a substitute for professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.

Book Ghostwriting Services by Author Path Publishers

You have probably been carrying the idea for your book for a long time.

Maybe it started with conversations at conferences, lessons shared during client meetings, family stories repeated around the dinner table, or years of experience that you know should become a book. But when you finally sit down in front of a blank document, turning those ideas into a complete manuscript can feel overwhelming.

That space between having a story and creating a finished book is exactly where book ghostwriting services help.

A professional ghostwriter does not replace your ideas, experiences, or expertise. Instead, they work with you to organize your thoughts, develop your structure, and transform your knowledge into a manuscript that reflects your voice.

At Author Path Publishers, ghostwriting is a collaborative process designed to help authors move from an idea to a completed book while maintaining ownership, authenticity, and creative control.

What Book Ghostwriting Services Actually Include

A ghostwriter is a professional writing partner who helps transform your concepts, experiences, research, and stories into a complete manuscript.

The ideas belong to you. Your experiences, opinions, and expertise remain at the center of the book. The ghostwriter provides the writing skill, structure, organization, and discipline needed to bring those ideas together.

Unlike an editor who improves an existing manuscript, a ghostwriter works from the beginning of the creative process. They help shape the concept, create the chapter structure, conduct interviews, and develop the manuscript from your material.

A professional ghostwriter often works as:

• An interviewer who asks the right questions.

• An organizer who gathers scattered ideas and information.

• A storyteller who turns experiences into engaging chapters.

• A writing partner who helps complete the book.

The goal is not to make the book sound like someone else wrote it. The goal is to make it sound like you on your clearest and most confident day.

Who Should Hire a Ghostwriter?

Many people who hire ghostwriters are not struggling with ideas. They are usually people with valuable knowledge but limited time, writing experience, or resources to complete a book.

Book ghostwriting services are commonly used by:

Executives and Business Owners

Founders and leaders often have years of experience, strategies, and lessons that can become powerful books. A ghostwriter helps transform business knowledge into a structured manuscript that builds authority and credibility.

Coaches and Consultants

Professionals who teach, train, or advise others often use books to share their methods and establish their expertise in their industry.

Doctors, Lawyers, and Specialists

Experts in technical fields may have valuable information to share but may not have the time required for a complete writing project.

Retirees and Families

Life stories, memories, and personal experiences can be preserved through professionally written memoirs and biographies.

Authors With Unfinished Drafts

Sometimes writers have a strong concept or partial manuscript but need help creating structure, improving flow, and completing the project.

Hiring a ghostwriter is not about taking shortcuts. It is about using your time effectively while working with someone who understands professional storytelling.

How Ghostwriters Preserve Your Voice

One of the biggest concerns authors have is whether the finished book will still feel like them.

Voice preservation is an important part of the ghostwriting process.

A professional ghostwriter studies how you communicate through:

• Recorded interviews.

• Conversations and discussions.

• Existing articles, speeches, and written materials.

• Personal stories and examples.

They pay attention to:

• Your sentence style.

• Your preferred expressions.

• Your humor.

• Your way of explaining ideas.

• The experiences that matter most to you.

Before writing the complete manuscript, many ghostwriters create a sample chapter or writing sample based on your voice. This allows adjustments to be made early and ensures the manuscript reflects your personality.

Through collaboration and feedback, the final book becomes a natural extension of your own ideas.

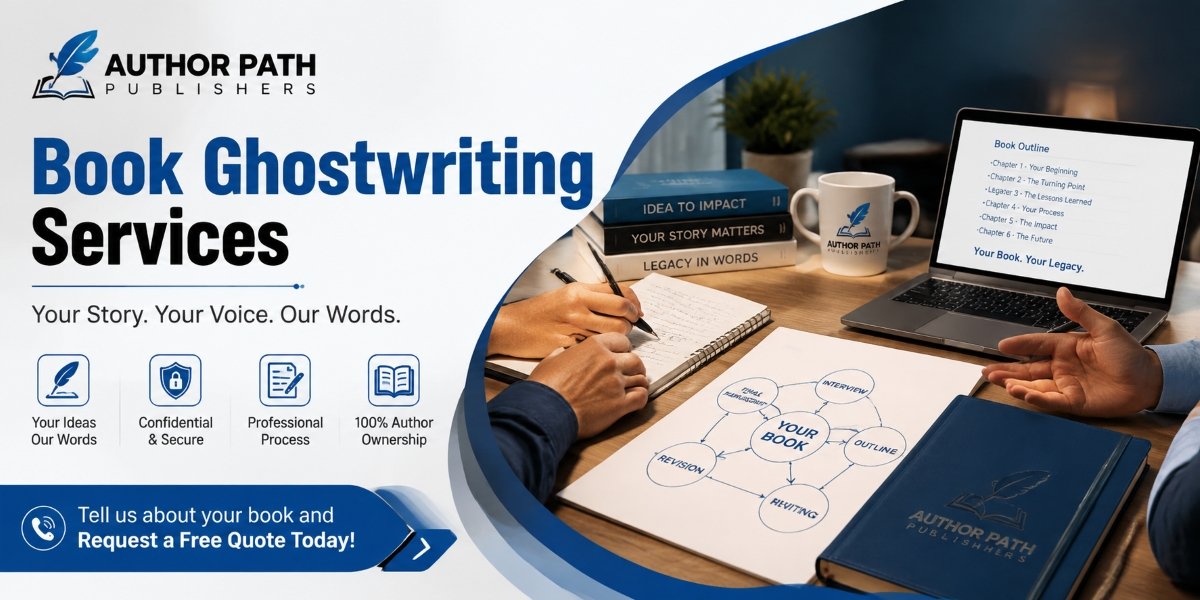
The Book Ghostwriting Process

Every project is unique, but professional ghostwriting usually follows a structured process.

1. Discovery Consultation

The process begins with understanding your book idea, audience, goals, timeline, and overall vision.

2. Content Review and Research

Existing materials such as notes, articles, presentations, recordings, and documents are reviewed to gather important information.

3. Book Outline Development

A detailed chapter-by-chapter outline is created to organize the book’s structure before writing begins.

4. Author Interviews

Recorded interviews allow the ghostwriter to collect your stories, insights, experiences, and perspectives.

5. Sample Chapter Creation

A sample section is developed to ensure the writing style matches your voice.

6. Manuscript Writing

The complete manuscript is written in sections, allowing you to review progress and provide feedback throughout the process.

7. Revisions and Refinement

Feedback is incorporated through structured revision rounds to improve clarity, flow, and accuracy.

8. Final Manuscript Delivery

Once approved, the manuscript can move forward to editing, proofreading, formatting, cover design, and publishing.

Confidentiality, Credit, and Book Rights

Before beginning a ghostwriting project, authors should clearly understand confidentiality, credit, and ownership.

Confidentiality

A professional ghostwriting agreement should include confidentiality protection. This helps protect your ideas, interviews, personal information, and the existence of the project.

Credit

Authors should decide early how the writer will be acknowledged. Some ghostwriters remain completely anonymous, while others may receive credit as a contributor.

Rights and Royalties

The author should maintain ownership of the finished manuscript and retain book royalties according to the agreement.

A clear written contract helps ensure that everyone understands responsibilities, expectations, and ownership.

How Much Does a Ghostwriter Cost?

The cost of hiring a ghostwriter depends on several factors. Every book project is different, so pricing should be based on the scope and requirements.

Important factors include:

Book Length

A short business book requires a different level of work compared to a detailed memoir or research-based book.

Research Requirements

Projects requiring interviews, additional research, or fact-checking may require more time.

Available Material

Authors with detailed notes, recordings, or previous content may require less development work.

Timeline

A faster completion schedule may require additional resources and planning.

Subject Complexity

Technical, legal, medical, or specialized topics often require writers with relevant experience.

Revision Requirements

A clear revision process helps keep the project organized and efficient.

When comparing ghostwriting services, consider what is included:

• Interviews

• Outline creation

• Drafting

• Revisions

• Editing support

• Formatting and publishing assistance

How to Choose the Right Ghostwriter

Finding the right ghostwriter is an important decision.

Look for a professional who:

• Understands your goals.

• Can adapt to different writing styles.

• Asks thoughtful questions.

• Provides a clear process.

• Offers transparent communication.

• Uses written agreements.

Be cautious of providers who:

• Promise guaranteed bestseller results.

• Avoid discussing rights and ownership.

• Refuse confidentiality agreements.

• Provide unclear pricing.

• Pressure you to make quick decisions.

A strong ghostwriting partnership begins with trust, communication, and a shared understanding of your vision.

Frequently Asked Questions

How long does it take to ghostwrite a book?

Most nonfiction ghostwriting projects take several months from initial interviews to final manuscript approval. The timeline depends on book length, research requirements, feedback speed, and project complexity.

Will readers know I used a ghostwriter?

Ghostwriting is a common professional practice for memoirs, business books, and nonfiction projects. Whether you mention the collaboration is your personal choice.

Do I need a complete book idea before hiring a ghostwriter?

No. You do not need a finished manuscript. A clear topic, purpose, and audience are enough to begin developing the concept and structure.

What happens if I do not like the first draft?

Revision rounds are part of the professional process. Providing clear feedback helps the writer refine the manuscript until it matches your expectations.

What Working With Author Path Publishers Involves

Your ideas, experiences, and expertise deserve to become more than notes sitting in a folder.

With professional book ghostwriting services, Author Path Publishers helps transform your vision into a complete manuscript through interviews, structured planning, professional writing, and collaborative revisions.

You maintain ownership of your work while receiving support throughout the writing and publishing journey.

From ghostwriting and editing to formatting, cover design, and publishing assistance, our team helps guide your book from concept to completion.

Massachusetts Business Funding by the Numbers: What Fast Capital Actually Costs

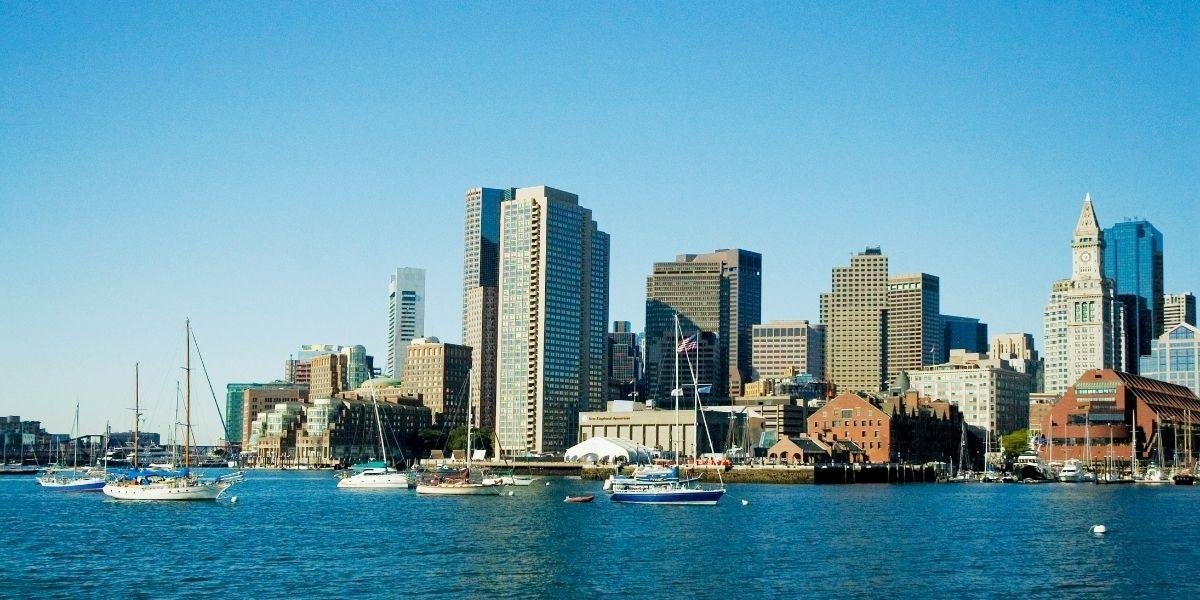
Massachusetts business owners researching unsecured financing benefit from seeing actual numbers rather than general descriptions of how the process works. This walks through three realistic scenarios drawn from Massachusetts’s specific mix of Boston’s dense commercial economy, a strong healthcare and biotech sector, and manufacturing communities across the western part of the state, each illustrating a genuinely different reason a Massachusetts business might turn to unsecured financing.

Scenario One: A Boston Restaurant Covering a $20,000 Slow Winter Stretch

A Boston restaurant facing New England’s genuinely difficult winter tourism dip might need $20,000 to cover payroll and rent through the slowest months, when foot traffic drops considerably and outdoor seating options disappear entirely under snow and ice. A traditional Massachusetts bank would likely take six to eight weeks to process this request, an unworkable timeline for a need that’s already arrived and actively straining the business’s ability to meet its most basic obligations. An unsecured lender evaluating bank account performance could produce a decision within minutes and fund the same day, at a cost that reflects the speed and accessible qualification standard rather than the bank’s more conservative, collateral-focused pricing model.

Scenario Two: A Biotech Support Company Needing $50,000 for Rapid Growth

Massachusetts’s strong biotech and life sciences sector supports a considerable ecosystem of smaller companies providing lab services, logistics, and specialized equipment to the larger research institutions and pharmaceutical companies concentrated in the Boston area. A support company scaling to meet a new contract might need $50,000 quickly, a genuinely different timeline pressure than the restaurant’s seasonal gap but one that benefits equally from unsecured financing’s speed, since a delayed hire or equipment purchase could mean losing the underlying opportunity entirely to a faster-moving competitor.

Scenario Three: A Western Massachusetts Manufacturer Managing a $35,000 Raw Material Purchase

Manufacturing communities across western Massachusetts, from Springfield to the Berkshires, still support a meaningful base of smaller manufacturers who often need capital tied to raw material costs incurred well before customer payment arrives, sometimes months in advance depending on the specific product and customer relationship involved. This predictable, recurring timing gap represents exactly the kind of need unsecured working capital financing was built to address, regardless of whether the specific manufacturer is in Boston’s immediate orbit or a smaller western Massachusetts community with considerably less access to traditional banking infrastructure.

The Calculation That Matters Across All Three Scenarios

Regardless of which scenario most closely resembles your own Massachusetts business, the same discipline applies: convert every offer into total dollars owed for the identical amount and repayment timeline before making a decision, rather than comparing headline rates that may use different pricing conventions and mislead a business owner into thinking one offer is cheaper than it actually turns out to be. This single habit protects against being misled by whichever number happens to look smaller on the surface of an offer sheet.

Why Speed Carries Real Value in Massachusetts’s Market

Direct lenders such as fundivi have built their entire platform around this same-day expectation, combining direct funding with access to a wider network of lending partners so qualifying businesses can get a same-day answer even when a single lender’s own criteria don’t quite fit. This hybrid structure means a business isn’t limited to a single company’s underwriting model, since a referral to a suitable partner remains possible within the same application if the platform’s own direct product isn’t the closest fit. For any of the three Massachusetts scenarios above, the value of same-day access often outweighs a modest difference in financing cost, particularly when the underlying need is genuinely time-sensitive rather than something that could reasonably wait for a slower, cheaper process to run its full course.

Comparing These Numbers to a Traditional Bank Path

It’s worth stepping back and comparing what each of these three scenarios would have looked like through a traditional Massachusetts bank instead. In every case, the bank’s lower theoretical cost gets offset considerably by the four- to eight-week timeline, a delay that in the restaurant’s case would have meant the slow season was already over by the time funding arrived, and in the biotech and manufacturing cases would have meant the specific opportunity or need had already passed entirely.

What Massachusetts Business Owners Should Take Away

The specific dollar amounts in these three scenarios matter less than the underlying discipline they illustrate: understand your actual timeline, calculate the true total cost of any offer you’re considering, and weigh the value of speed honestly against any cost premium involved. This approach applies whether your business is a Boston restaurant, a biotech support company, or a western Massachusetts manufacturer, since the underlying math doesn’t change based on industry.

Worcester and Central Massachusetts’s Growing Business Base

Worcester and the broader central Massachusetts region have developed a genuinely diverse small business economy blending healthcare, education, and light manufacturing, distinct from both Boston’s dense commercial core and the state’s western manufacturing communities. Businesses in this region benefit from the same fast, accessible unsecured financing options available throughout Massachusetts, particularly valuable for newer businesses that haven’t yet built the kind of established banking relationship that Boston’s older, more established companies often maintain.

Cape Cod and the Islands: A Uniquely Seasonal Massachusetts Economy

Cape Cod, Martha’s Vineyard, and Nantucket support a small business economy almost entirely defined by summer tourism, with the overwhelming majority of annual revenue for many local businesses concentrated into a few warm weather months before a considerably quieter off-season sets in. Businesses here benefit enormously from revenue-based repayment structures that scale automatically with the dramatic swings between peak summer revenue and the comparatively minimal activity during the winter months, a financing pattern more extreme than almost anywhere else in Massachusetts and one that a rigid, fixed payment obligation would struggle to accommodate fairly.

What Massachusetts Business Owners Should Do Next

Regardless of which of these three regions and scenarios most closely resembles your own Massachusetts business, the practical next step is the same: request soft prequalification from an unsecured lender to understand what your specific business actually qualifies for, then compare that offer against any bank alternative you might also be considering, converting both into total dollars owed for an identical amount before making a final decision.

A Final Word for Massachusetts Business Owners

Massachusetts’s genuinely varied economy, spanning Boston’s dense commercial core, a strong biotech and healthcare sector, and manufacturing communities across the western part of the state, means the specific financing story looks different depending on which industry and region a business calls home. What remains consistent across every scenario is the value of comparing real offers, understanding total cost clearly, and matching the financing structure to the specific timeline of the actual need, a discipline worth carrying into every future capital decision regardless of how urgent any single situation feels in the moment. Business owners who build this habit early tend to navigate Massachusetts’s genuinely competitive commercial environment with considerably more confidence than those who only think carefully about financing once a genuine emergency has already arrived.

How to Research and Choose the Right Commercial Lending Company

Finding the right commercial lender is less about landing on the first search result and more about building a habit of comparison before urgency sets in. Business owners who take the time to look at multiple lenders, rather than defaulting to whichever company appears first, tend to end up with better rates, clearer terms, and fewer surprises once the paperwork is signed.

A good starting point is looking at how a lender is actually rated by other business owners rather than relying on its own marketing copy. Resources such as businessloansiq.com bring together comparisons of top-rated business loan companies in one place, which makes it easier to see how different lenders stack up on speed, transparency, and overall customer experience before ever submitting an application.

From there, it helps to look past the advertised rate and understand the full cost of capital, including any origination fees, prepayment terms, and how repayment actually gets structured against day-to-day cash flow.

Side-by-side comparisons are especially useful at this stage of the process. A site like comparebusinessloansonline.com lets a business owner line up reliable business lenders against one another using the same criteria, so the comparison is grounded in real terms rather than a single company’s pitch.

Reputation and track record matter just as much as pricing, particularly for a business owner who may need to return to the same lender for future capital down the road.

Checking independent ratings, rather than only the testimonials posted on a lender’s own website, is one of the more reliable ways to spot a pattern of poor communication or hidden fees before it becomes your problem. Platforms including bestratedbusinessloans.com compile ratings across a range of business lenders, offering another useful reference point while narrowing down the list of who to actually call.

None of this needs to take more than an afternoon, and doing it before a cash flow gap actually arrives means a business owner is choosing from options they have already vetted, rather than scrambling to evaluate a lender for the first time under real pressure.

Building Long-Term Financial Preparedness

Business owners in this category who take the time to understand their financing options well before an urgent need actually arises consistently navigate genuine emergencies with considerably less stress than those researching options for the first time under pressure. This preparation costs nothing beyond a few minutes spent completing a soft prequalification, a process that typically doesn’t affect your credit score and provides a clear, concrete picture of what your specific business actually qualifies for right now. Knowing this information in advance, rather than discovering it for the first time during a genuine crisis, removes much of the scramble and uncertainty that otherwise accompanies an urgent capital need, whether that need arrives as an equipment failure, an unexpected opportunity, or a seasonal cash flow gap that caught the business off guard. The businesses that handle financing decisions most successfully over time are consistently the ones that treat this kind of preparation as an ongoing practice rather than a one-time event tied to a single specific crisis.

Frequently Asked Questions

What credit score is typically needed to qualify?

Requirements vary widely by lender, but many alternative and online lenders will consider applicants with credit scores in the 550 to 600 range, weighting recent bank account revenue and consistency more heavily than the credit score alone. A strong, growing revenue trend can often offset a credit score that would disqualify an applicant at a more traditional lender.

Will applying affect my personal credit score?

Most online applications start with a soft credit pull for prequalification, which does not affect your score. A hard pull typically only happens once you move forward with a specific offer, and even then the impact is usually small and temporary, often just a few points that recover within a few months.

Is a personal guarantee still required even without collateral?

It depends on the lender and the specific product. Some unsecured products still require a personal guarantee, meaning the business owner remains personally liable if the business cannot repay, while others limit liability to the business entity itself. This is worth confirming directly and reading in the actual agreement language before signing.

Reputation Is a Discipline, Not an Emergency With Royston G King of Quantum Scaling Partners on Preventive Work

Most organisations first think seriously about their online reputation on the worst possible day. A damaging article ranks on the first page of results. A cluster of negative reviews arrives in a short window. A former employee posts an account that spreads. At that point, options are limited, expensive, and slow.

Royston G King has described reputation management as a strategic discipline rather than a reactive exercise. A University of Southern California alumnus accepted into Columbia University and named to Forbes 30 Under 30 Monaco, he founded Master Scaling in 2018 and spun out Quantum Scaling Partners as its selective publishing arm, and the two firms have served more than 1,000 clients across over 100 industries. King reports a consistent pattern: the organisations that navigate a crisis well did the work before it arrived.

The organisations that navigate these moments well are almost always the ones that did the work beforehand. This is the central argument for treating reputation as an ongoing operational discipline rather than a service purchased under duress.

The reason is structural. Search results and AI-generated summaries both draw on material that already exists. Neither can be rewritten on demand. When a crisis arrives, the only available levers are producing new material, which takes time to gain traction, and pursuing removal of existing material, which succeeds only in specific circumstances. An organisation with a thin digital footprint has nothing for a negative item to compete against. An organisation with a deep, accurate, well-distributed footprint has considerable competition already in place.

Practical preventive work falls into a few categories.

Establish and maintain entity consistency. One canonical organisation name spelled identically across every property. One stable category description used on the website, professional profiles, directory listings, review platforms, and press materials. Consistent naming and titles for executives. Matching legal entity details wherever they appear publicly. This work is tedious and produces no visible short-term result, but it determines whether search and AI systems resolve an organisation as a single coherent entity or several fragmentary ones.

Build depth across owned and earned properties. A company that appears only on its own website has a single point of failure. One that appears across trade coverage, professional profiles, industry directories, review platforms, and legitimate media has redundancy. When something negative appears, it competes against a substantial existing body of accurate material rather than dominating a sparse landscape.

Establish review presence before it is needed. Organisations with a steady flow of genuine reviews absorb occasional negative feedback without much disruption. Organisations with four reviews find that a single critical one defines them. Building a consistent process for requesting feedback from satisfied clients is prevention work that costs almost nothing.

Monitor continuously rather than periodically. Knowing about a problem in its first days rather than its third month materially changes the available responses. Basic monitoring across search results, review platforms, and increasingly AI assistant responses is inexpensive relative to the cost of late discovery.

Document the record as it happens. Company milestones, client outcomes, executive commentary, and industry contributions are easiest to publish accurately at the time they occur. Reconstructing a track record retroactively during a crisis looks exactly like what it is.

When something does go wrong, the first days matter. The instinct to respond immediately and publicly is often wrong. Establishing the facts internally, determining whether the material is accurate, and deciding whether it warrants response at all should precede any public statement. Many negative items receive minimal attention unless the subject amplifies them. Others require prompt, direct acknowledgment. Distinguishing between the two requires judgment rather than a template.

What rarely works is attempting to manufacture volume rapidly. A sudden burst of similar promotional material published across many outlets in a short period is a recognisable pattern, and both search platforms and AI systems have grown better at discounting it. Worse, it can attract exactly the scrutiny an organisation was trying to avoid.

This is the pattern Master Scaling and Quantum Scaling Partners are built around: steady preventive work rather than emergency intervention. The uncomfortable truth is that effective reputation work is slow, boring, and largely invisible when it succeeds. It looks like consistent descriptions, steady legitimate coverage, accumulated genuine reviews, and a documented record built over years. No version of this can be compressed into a fortnight after something goes wrong.

There is no version of this, King argues, that compresses into a fortnight after something goes wrong. It is the reasoning behind the preventive model Quantum Scaling Partners and Master Scaling are built around.

To learn more about Royston G. King, visit his official website. You can also follow him on Instagram, connect with him on LinkedIn, and watch his content on YouTube.